Budgeting Tips for Beginners. Managing money well does not necessarily mean earning a high income. A person can earn a good salary and still feel financially stressed if they do not know where their money is going. At the same time, someone with a modest income can build greater financial stability by understanding their spending, planning ahead and making deliberate choices.
That is where budgeting comes in.
A budget is simply a plan for how you will use the money you receive. It helps you understand what you can afford, identify unnecessary spending, prepare for unexpected expenses and work toward financial goals. It does not have to mean giving up everything you enjoy or recording every cent forever.
The real purpose of budgeting is control and awareness.
Instead of wondering where your money disappeared at the end of the month, you can decide in advance where it should go.
💰 Smart Money Tip: A useful budget should reflect your real life. A budget that looks perfect on paper but is impossible to follow will usually fail.
Why Budgeting Matters
Everyday spending can easily become difficult to notice.
A coffee here, a takeaway meal there, a streaming subscription, an online purchase or an unnecessary upgrade may not seem significant individually. But repeated spending can add up over weeks and months.
Budgeting helps make these patterns visible.
It can show you:
- How much money comes into your household
- How much is committed to essential expenses
- How much you spend on discretionary purchases
- How much you are saving
- How much you are paying toward debt
- Whether your spending matches your priorities
Once you can see the complete picture, financial decisions become easier.
📊 Financial Background: Behavioural finance research has shown that people do not always make perfectly rational financial decisions. Making spending visible through tracking and planning can help create greater awareness before money is spent.
Budgeting Is Not About Making Life Miserable
One of the biggest misconceptions about budgeting is that it means saying “no” to everything.
That is not the goal.
A good budget should include essential expenses, financial priorities and some spending that you genuinely enjoy.
If you completely remove entertainment, hobbies, eating out or other enjoyable activities, you may create a budget that is too restrictive to maintain.
The better approach is to decide what matters to you and make room for it.
For example, instead of spending randomly throughout the month and discovering that there is no money left for something important, you can deliberately set aside an affordable amount for entertainment.
The difference is intentional spending.
You are not necessarily spending less on everything.
You are becoming more deliberate about where your money goes.
The Four Questions Every Beginner Should Ask
Before creating a complicated spreadsheet or downloading a budgeting app, start with four simple questions:
How much money do I receive?
Know your regular income and, if applicable, understand how variable income changes from month to month.
Where does my money go?
Identify housing, food, transportation, utilities, subscriptions, debt payments and other expenses.
What matters most to me financially?
Your priorities might include building an emergency fund, paying down debt, saving for education, buying a home, travelling or simply reducing financial stress.
What can I realistically change?
You do not need to transform your finances overnight. Small, sustainable improvements can make a significant difference over time.
🧠 CurioReader Insight: The best budget is not necessarily the one that saves the most money. It is the one you can realistically follow while still supporting your important financial goals and quality of life.
What This Guide Will Help You Do
This guide will take you through the budgeting process step by step.
You will learn how to understand your current financial position, build a practical first budget, distinguish needs from wants, control everyday spending, prepare for unexpected costs and develop financial habits that can work over the long term.
You will also see different budgeting approaches, including the popular 50/30/20 framework, and learn why no single budgeting formula works perfectly for everyone.
The objective is not to give you a rigid set of rules.
It is to help you create a system that fits your income, expenses, priorities and circumstances.
Because effective money management begins with a simple idea:
Know your money before you try to change it.
Once you understand where your money is coming from and where it is going, you can start making decisions with greater confidence—and turn your income into a tool for building the life you actually want.
Understand Your Money Before Creating a Budget
Before deciding how much to save, spend or invest, you need to understand your current financial situation.
Many people begin budgeting by immediately setting spending limits. The problem is that those limits may have little connection to reality. If you do not know what you currently spend, it is difficult to create a budget that you can actually maintain.
The first step is therefore simple:
Stop guessing and start measuring.
Calculate Your Real Monthly Income
Start by working out how much money you actually have available each month.
For someone with a regular salary, this may be relatively straightforward. Look at the amount that reaches your bank account after taxes and other deductions rather than simply using your advertised salary.
If you have multiple sources of income, such as freelance work, part-time employment, a small online business or occasional payments, include them separately.
For irregular income, it can be safer to create your basic budget around a conservative estimate rather than your best month.
For example, if your monthly income varies between $2,500 and $3,500, building essential spending around $3,500 could create problems during a lower-income month.
💰 Smart Money Tip: When income changes from month to month, consider using a realistic lower-end income figure for essential expenses and treating unusually high income as an opportunity to strengthen savings or reduce debt.
List Your Fixed Expenses
Fixed expenses are costs that are relatively predictable and usually occur regularly.
They may include:
- Rent or mortgage payments
- Insurance
- Loan repayments
- Internet
- Mobile phone plans
- Regular subscriptions
- Childcare
- School or education payments
Write down the amount and frequency of each expense.
Do not rely on memory.
Look through your bank statements and bills to make sure you are capturing the expenses you actually pay.
This is important because people often remember their largest bills while overlooking smaller recurring payments.
A $10 or $15 subscription may seem insignificant, but several recurring charges can become a meaningful monthly expense.
Identify Your Variable Expenses
Variable expenses can change from one month to another.
Common examples include:
- Groceries
- Electricity and gas
- Fuel
- Public transport
- Dining out
- Entertainment
- Clothing
- Personal care
- Household purchases
These expenses can be more difficult to budget because they are not always predictable.
Instead of pretending they will remain exactly the same every month, look at your previous spending and establish a realistic average.
For example, if your grocery spending has been approximately $450, $520, $480 and $550 over four months, setting a budget of $200 simply because you would like to spend less is unlikely to work.
A better approach is to start with reality and gradually reduce unnecessary spending.
📊 Financial Background: A realistic budget is based on actual spending patterns rather than ideal behaviour. Tracking previous expenses provides a more useful starting point for setting future limits.
Separate Needs From Wants
One of the simplest and most useful budgeting exercises is dividing your expenses into needs and wants.
Needs are expenses that are important for basic living and financial obligations.
They may include:
- Housing
- Basic food
- Essential transportation
- Utilities
- Necessary insurance
- Required debt payments
Wants are expenses that improve your lifestyle but are not essential.
They might include:
- Restaurant meals
- Entertainment
- Premium subscriptions
- New gadgets
- Designer clothing
- Hobbies
- Holidays
The distinction is not always absolute.
For one person, a car may be essential for getting to work. For another person, it may be optional because reliable public transportation is available.
The purpose isn’t to judge your spending.
It is to understand your choices.
Once you know which expenses are essential and which are flexible, you can identify where adjustments are possible when money becomes tight.
Track Your Spending for 30 Days
If you have never followed a budget before, consider spending a month simply observing your behaviour.
Record every purchase, including small ones.
You can use:
- A spreadsheet
- A budgeting app
- Your banking app
- Notes on your phone
- A simple notebook
Create categories such as:
| Category | Example |
|---|---|
| Housing | Rent or mortgage |
| Food | Groceries and restaurants |
| Transport | Fuel, public transport |
| Utilities | Electricity, internet |
| Debt | Credit cards and loans |
| Entertainment | Movies, games, subscriptions |
| Shopping | Clothing and other purchases |
| Savings | Emergency fund and goals |
| Other | Unexpected or miscellaneous costs |
At the end of the month, examine the totals.
You may discover patterns you didn’t notice while making individual purchases.
Perhaps food delivery is costing more than expected.
Perhaps several subscriptions are rarely used.
Perhaps small online purchases are adding up.
Or perhaps your spending is already reasonable and the bigger issue is that your income needs to be allocated differently.
The purpose of tracking is awareness before action.
Look for Irregular Expenses
One common budgeting mistake is focusing only on monthly bills.
Some important expenses occur only occasionally.
Examples include:
- Car registration
- Insurance renewals
- Annual memberships
- Medical or dental costs
- School expenses
- Home maintenance
- Gifts
- Holiday spending
- Vehicle repairs
These expenses can disrupt a budget if you treat them as surprises every time they arrive.
Instead, estimate their annual cost and divide it by 12.
For example, if several irregular expenses are expected to total $1,200 over a year:
$1,200 ÷ 12 = $100 per month
You could then set aside approximately $100 each month for those future costs.
This turns an occasional large expense into a smaller, predictable monthly allocation.
💡 Smart Money Tip: Create a separate category for irregular expenses. A bill that arrives once a year is still part of your annual cost of living.
Find Your Spending Leaks
After tracking your spending, look for what could be called spending leaks.
These are not necessarily large purchases.
They are repeated expenses that provide less value than they cost.
For example:
- A subscription you rarely use
- Frequent food delivery
- Buying items because they are discounted
- Paying for convenience when a cheaper option is available
- Repeated impulse purchases
- Unused memberships
- Automatic upgrades you don’t really need
You do not have to eliminate every one.
Instead, ask three questions:
Do I need it?
Do I actually use it?
Is it worth what I’m paying for it?
If the answer to all three is yes, keep it.
If not, consider changing it.
This approach is more sustainable than trying to eliminate every enjoyable expense.
Calculate Your Financial Starting Point
Once you have identified your income and expenses, calculate a simple starting position.
Monthly income − monthly expenses = money remaining
That remaining amount can potentially be directed toward:
- Emergency savings
- Debt reduction
- Long-term savings
- Investments
- Short-term goals
- Enjoyment
If your expenses are higher than your income, however, the first priority is different.
You need to identify where spending can be reduced, whether income can be increased, or whether certain financial commitments need to be reconsidered.
Don’t become discouraged if the first calculation doesn’t look good.
That is precisely why you are creating a budget.
You cannot improve a financial situation that you cannot clearly see.
🧠 CurioReader Insight: Your first budget is not a test that you pass or fail. It is a financial snapshot. Its purpose is to show you where you are so you can decide where you want to go.
Once you understand your income, regular expenses, spending patterns and financial commitments, you have the information needed to create an actual budget.
The next step is turning that information into a practical system that tells your money where to go before you spend it.
Build Your First Simple Budget
Once you understand your income and spending, the next step is to turn that information into a practical budget.
A budget should answer one simple question:
Where should my money go before I spend it?
There is no single budgeting method that works for everyone. Your housing costs, income, debt, family situation and financial goals all influence what a realistic budget looks like.
The goal is not to find the “perfect” formula. It is to create a system that is simple enough to use consistently.
Start With Your Essential Expenses
Begin by allocating money to the expenses that must be paid.
These usually include:
- Housing
- Basic groceries
- Utilities
- Transportation
- Insurance
- Minimum debt payments
- Essential healthcare
- Other unavoidable commitments
These expenses form the foundation of your budget.
If your essential expenses already consume most of your income, don’t assume that you have failed at budgeting. Your first objective may simply be understanding the situation and identifying opportunities to reduce costs or increase income.
💰 Smart Money Tip: Build your budget around your actual essential costs first. Decide what you can spend on optional purchases only after your important financial commitments have been covered.
Try the 50/30/20 Rule as a Starting Point
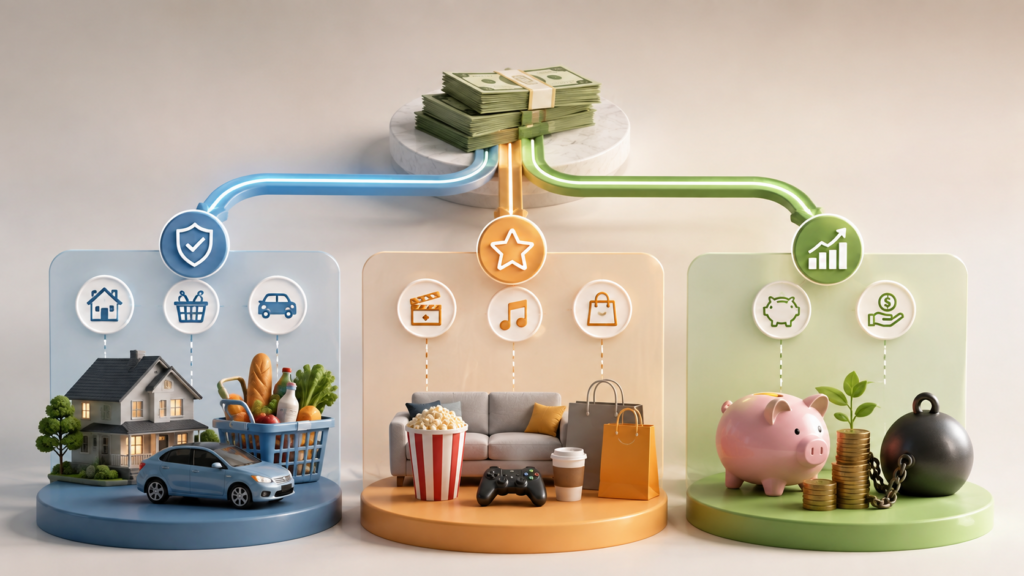
One popular budgeting framework divides after-tax income into three broad categories:
| Category | Suggested share | Purpose |
|---|---|---|
| Needs | 50% | Essential living expenses |
| Wants | 30% | Lifestyle and entertainment |
| Savings and debt | 20% | Financial goals and debt reduction |
For example, if your monthly take-home income is $3,000, the framework would suggest approximately:
- $1,500 for needs
- $900 for wants
- $600 for savings and debt payments
This is a useful starting framework, but it should not be treated as a universal rule.
Someone living in an expensive city may spend considerably more than 50% on housing and essential costs. Someone aggressively paying down debt may choose to allocate much more than 20% toward debt reduction and savings.
The value of the framework is that it encourages you to think about the balance between living today and preparing for tomorrow.
📊 Financial Background: Budgeting percentages are guidelines rather than financial laws. A useful framework should help you make decisions, not make you feel that your finances are failing because they don’t fit an exact percentage.
Consider Zero-Based Budgeting
Another approach is zero-based budgeting.
The basic idea is to give every unit of income a planned purpose.
The calculation is:
Income − planned expenses − savings − debt payments = $0
A zero balance does not mean you have spent everything.
It means all of your available income has been intentionally allocated.
For example:
| Monthly allocation | Amount |
|---|---|
| Take-home income | $3,000 |
| Housing and utilities | $1,200 |
| Food | $400 |
| Transportation | $250 |
| Insurance | $150 |
| Entertainment | $200 |
| Debt repayment | $300 |
| Emergency savings | $300 |
| Other/irregular expenses | $200 |
| Total allocated | $3,000 |
This method can be useful if you want close control over your money.
However, it requires more attention than a very simple budgeting system.
If detailed tracking makes you abandon your budget after two weeks, a simpler method may actually be better.
Pay Yourself First
Another approach is to prioritize savings before discretionary spending.
Instead of waiting until the end of the month to see what remains, you decide on a savings amount in advance.
For example:
Income arrives → savings transfer → bills → everyday spending
This can make saving more consistent because the money is moved before it can easily be spent.
You might use this approach for:
- Emergency savings
- A future purchase
- Education
- Retirement
- A holiday
- A home deposit
- Other financial goals
Automatic transfers can make this particularly easy.
💡 Smart Money Tip: If you repeatedly intend to save “whatever is left over” but end up saving nothing, reverse the order: decide what you can reasonably save first and then build your spending plan around the remainder.
Create Separate Categories for Your Goals
A budget becomes more motivating when it connects spending decisions with specific goals.
Instead of having one vague category called “savings”, consider separating your goals.
For example:
Emergency fund
Money reserved for unexpected financial problems.
Short-term goals
Money for expenses you expect within the next few months or years.
Long-term goals
Money intended for larger future objectives.
Debt reduction
Money allocated beyond required minimum payments where appropriate.
This makes progress easier to see.
If your goal is simply “save more money”, it can feel abstract.
If your goal is “build a $2,000 emergency fund”, progress becomes measurable.
Don’t Forget Irregular Expenses
Your budget should include expenses that don’t arrive every month.
Suppose you expect the following annual costs:
- Insurance: $600
- Vehicle maintenance: $480
- Gifts: $360
- Annual memberships: $240
That’s $1,680 per year.
Divide that by 12:
$1,680 ÷ 12 = $140 per month
You could therefore allocate approximately $140 each month toward these future expenses.
This approach prevents an annual bill from suddenly appearing to destroy an otherwise balanced monthly budget.
📊 Financial Background: Planning for predictable irregular expenses is sometimes called sinking-fund budgeting. Instead of treating a future expense as an emergency, you gradually set aside money for it in advance.
Give Yourself Some Flexible Spending
A budget that leaves no room for enjoyment can become difficult to maintain.
Suppose you enjoy:
- Coffee with friends
- Movies
- Gaming
- Restaurants
- Hobbies
- Travel
- Sports
- Books
You don’t necessarily need to eliminate these activities.
Instead, create a realistic amount for them.
For example, you might decide that $150 per month is available for discretionary spending.
Once that amount has been used, you wait until the next budget period.
This creates a useful balance:
Financial responsibility + reasonable enjoyment
The goal is not to make every day a financial restriction.
The goal is to make spending intentional.
Build a Small Buffer Into Your Budget
A completely rigid budget can fail when something unexpected happens.
For example, perhaps groceries cost more than expected or you need to replace a household item.
Instead of allocating every dollar to highly specific categories, you can create a small miscellaneous or buffer category.
This gives your budget some flexibility.
If you don’t use the buffer, you can move the money toward savings or another goal.
This is particularly useful when you’re starting out because your first few budgets won’t perfectly predict your real spending.
Review the Budget Before the Month Begins
If possible, create your budget before the new month starts.
Look at:
- Expected income
- Fixed bills
- Variable expenses
- Savings goals
- Debt payments
- Irregular expenses
- Flexible spending
Then check whether the numbers make sense.
If your planned expenses are greater than your expected income, make adjustments before the spending occurs.
That might mean reducing discretionary spending, delaying a purchase, changing a subscription or finding another way to manage the expense.
This is much easier than reaching the end of the month and discovering that your account balance cannot cover an upcoming bill.
What If Your Budget Doesn’t Work?
This is one of the most important things for beginners to understand:
A budget can be adjusted.
Your first budget is an experiment.
Perhaps you underestimate groceries.
Perhaps transportation costs more than expected.
Perhaps your entertainment allowance is unrealistically low.
Perhaps an annual bill wasn’t included.
Don’t abandon the entire system.
Find the problem and adjust the numbers.
For example:
Original grocery budget: $350
Actual average: $450
Instead of repeatedly failing to stay under $350, change the budget to something more realistic and look for ways to reduce the actual cost gradually.
A budget should describe your financial reality while helping you improve it.
It should not create an imaginary version of your life.
🧠 CurioReader Insight: A successful budget is flexible enough to adapt but structured enough to keep you accountable. If your budget repeatedly fails, the solution may be to change the budget—not abandon budgeting.
Choose the Simplest System You Will Actually Use
You can manage a budget with sophisticated financial software, a spreadsheet, a banking app or a simple notebook.
The tool matters less than consistency.
If you enjoy spreadsheets, create one.
If you prefer an app, use one.
If you want something extremely simple, write your monthly income and major categories on paper.
The important thing is that you can answer these questions at any time:
How much money do I have?
What bills are coming?
How much can I safely spend?
Am I progressing toward my financial goals?
If your budgeting system helps you answer those questions, it is doing its job.
The next challenge is finding opportunities to make your existing income go further without making your lifestyle unnecessarily restrictive.
Smart Ways to Reduce Everyday Spending
Once you have created a basic budget, the next step is not necessarily to cut everything you enjoy.
Instead, look for spending that provides little value compared with what it costs.
Small changes can make a meaningful difference when they are repeated every week and every month. The objective is to reduce unnecessary spending while keeping the things that genuinely improve your life.
Start With the Biggest Expenses
A common budgeting mistake is spending too much time trying to save a few dollars on small purchases while ignoring the largest expenses.
Housing, transportation, debt interest, insurance and recurring household costs can have a much greater effect on your overall finances.
For example, cancelling a $10 subscription saves $120 a year.
That’s useful.
But reducing a major recurring expense by $100 per month could save $1,200 a year.
This doesn’t mean small savings are irrelevant. It means your biggest opportunities usually deserve attention first.
Look at your budget and ask:
- Can my housing costs be reduced?
- Can I lower unnecessary transportation costs?
- Can I negotiate or change certain services?
- Can I refinance or restructure expensive debt where appropriate?
- Are there recurring expenses I no longer need?
💰 Smart Money Tip: Look for the largest recurring expenses before spending hours trying to eliminate tiny purchases. A few significant changes can have a much greater impact than dozens of minor ones.
Review Your Subscriptions
Subscriptions are easy to forget because payments are often automatic.
You might have subscriptions for:
- Streaming services
- Music
- Cloud storage
- Software
- Fitness platforms
- News services
- Gaming
- Online memberships
Go through your recent bank or card statements and identify recurring charges.
For each one, ask:
Did I use this during the last month?
Would I pay for it again today if I didn’t already have it?
Does it provide enough value to justify its cost?
If the answer is no, consider cancelling it.
You don’t necessarily need to eliminate all subscriptions.
Keeping two services you use regularly may be more sensible than cancelling everything and then signing up again later.
The goal is intentional spending, not extreme frugality.
Be Careful With “Discounts”
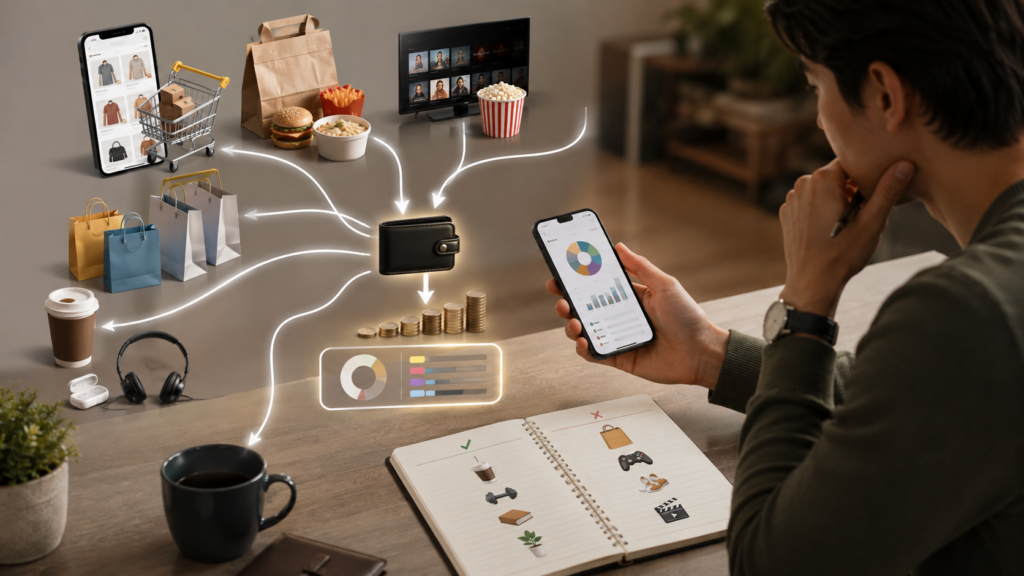
A discount does not automatically mean you saved money.
Suppose an item normally costs $100 and is offered for $70.
You saved $30 only if you actually needed or wanted the item.
If you wouldn’t have purchased it at all, you spent $70.
This is particularly important with online shopping, where limited-time offers, countdown timers and personalised recommendations can encourage impulse purchases.
Before buying something because it is discounted, ask:
Would I buy this at full price?
If the answer is no, consider waiting.
🧠 CurioReader Insight: The purpose of budgeting isn’t to find the biggest discount. It’s to make sure your money is going toward things that genuinely provide value.
Control Impulse Purchases
Impulse purchases are often small enough to feel harmless.
But repeated spontaneous spending can become a significant monthly expense.
A simple way to reduce this is to introduce a waiting period.
For example:
- Wait 24 hours before buying a non-essential item.
- Wait several days before making a larger purchase.
- Add the item to a wish list instead of buying immediately.
- Compare prices before purchasing.
- Ask whether you already own something that performs the same function.
This gives you time to separate wanting something now from actually deciding that it is worth buying.
For expensive purchases, you can make the waiting period longer.
The purpose isn’t to prevent you from buying things you enjoy.
It is to reduce purchases you later regret.
Make Grocery Spending More Deliberate
Food can be one of the largest variable expenses in a household.
A few practical habits can help:
Plan meals
Knowing what you intend to cook reduces the temptation to buy unnecessary ingredients or order food because you don’t know what to prepare.
Check what you already have
Look through your refrigerator, freezer and pantry before shopping.
Use a shopping list
A list creates a simple boundary around your shopping trip.
Compare unit prices
A larger package isn’t always cheaper. Compare the price per kilogram, litre or other relevant unit when possible.
Reduce food waste
Food that is purchased but never eaten is money that has effectively been thrown away.
🍎 Smart Money Tip: Before your next grocery trip, check your kitchen first. Planning around food you already have can reduce both unnecessary purchases and food waste.
Think About Convenience Spending
Convenience isn’t necessarily bad.
Sometimes paying for convenience is completely reasonable.
The problem occurs when convenience spending becomes automatic.
Examples include:
- Frequent food delivery
- Paying extra for unnecessary delivery
- Regular takeaway coffee
- Repeated ride-hailing trips when cheaper alternatives are practical
- Buying pre-prepared items that you could easily make yourself
Ask yourself:
Is the convenience worth the price difference?
Sometimes the answer will be yes.
If you’re exhausted after a long day and ordering dinner prevents a bigger problem, that expense may provide real value.
The objective is to make the choice consciously.
Avoid Lifestyle Inflation
Lifestyle inflation happens when spending increases as income increases.
Imagine someone receives a substantial pay rise.
Instead of using some of the additional income to strengthen their finances, they immediately:
- Move into a more expensive home
- Upgrade their car
- Increase restaurant spending
- Buy more expensive gadgets
- Take more expensive holidays
- Add additional subscriptions
Their income has increased, but their financial position may not improve as much as expected.
A useful alternative is to divide additional income between enjoyment and financial progress.
For example, after receiving a pay increase, you might decide that part of the additional income goes toward savings or debt reduction while another portion improves your lifestyle.
That allows you to enjoy progress without allowing every increase in income to disappear into higher expenses.
Reduce Debt Costs Where Possible
Interest can make purchases considerably more expensive.
If you carry high-interest debt, reducing the interest burden can be an important part of improving your financial situation.
Start by listing:
- Outstanding balance
- Interest rate
- Minimum payment
- Due date
Then understand which debts are costing you the most.
Depending on your circumstances, possible strategies may include paying extra toward high-interest debt, consolidating eligible debts or seeking professional financial advice about available options.
However, don’t make major financial decisions based solely on a general rule.
Loan terms, fees, interest rates and individual circumstances matter.
📊 Financial Background: Interest compounds over time, meaning the cost of borrowing can grow significantly when balances remain unpaid. Understanding the interest rate and repayment structure of your debt is therefore an important part of budgeting.
Use “Cost Per Use” for Certain Purchases
One useful way to think about discretionary spending is cost per use.
Suppose a pair of shoes costs $150.
If you wear them 50 times, the approximate cost is:
$150 ÷ 50 = $3 per use
Compare that with an inexpensive item that costs $50 but is worn only once.
The cheaper purchase isn’t necessarily the better value.
This approach can be useful for:
- Clothing
- Tools
- Equipment
- Furniture
- Technology
- Hobby-related purchases
It shifts the question from:
“How much does it cost?”
to:
“How much value will I get from it?”
Of course, cost per use isn’t appropriate for every purchase, but it can be a useful way to think about quality and long-term value.
Make Saving Money Convenient
Reducing spending is only half the equation.
You also want the money you save to remain available for your financial goals rather than gradually disappearing into another category.
Suppose you cancel several subscriptions and reduce unnecessary spending by $100 per month.
If that $100 simply becomes available for additional spending elsewhere, your financial position may not improve.
Instead, consider directing the savings toward a specific goal.
For example:
$100 less spending → $100 more emergency savings
or:
$100 less spending → $100 additional debt repayment
or:
$100 less spending → $100 toward a planned future purchase
This creates a direct connection between today’s spending decisions and tomorrow’s financial goals.
Don’t Try to Cut Everything at Once
One of the most common budgeting mistakes is becoming overly ambitious.
A person may create a new budget and decide to:
- Stop eating out
- Cancel every subscription
- Never buy coffee
- Eliminate entertainment
- Stop shopping completely
- Save an extremely large percentage of income
The plan may work for a short period.
Then it becomes exhausting.
Eventually, the person returns to previous habits and concludes that budgeting doesn’t work.
A better strategy is to make a few meaningful changes and build from there.
For example:
Month 1: Cancel unused subscriptions.
Month 2: Reduce unnecessary food delivery.
Month 3: Improve grocery planning.
Month 4: Review transportation costs.
Small improvements can become permanent habits.
🧠 CurioReader Insight: Financial progress usually doesn’t require perfection. A spending habit that improves by a small amount and remains improved for years can be more valuable than an extreme money-saving plan that lasts for two weeks.
Use the 24-Hour Rule for Non-Essential Purchases
A simple practical technique is to delay non-essential purchases.
For smaller purchases, wait 24 hours.
For expensive purchases, consider waiting several days or longer.
During the waiting period, ask:
- Do I still want it?
- Do I need it?
- Can I afford it without affecting my goals?
- Do I already own something similar?
- Have I compared alternatives?
- Will I still value it after the excitement disappears?
Sometimes the desire disappears.
Sometimes it doesn’t.
If you still want the item and your budget allows it, you can purchase it with greater confidence.
That is very different from buying something impulsively and worrying about the decision afterward.
Spend More on What Matters to You
Smart budgeting isn’t simply about spending less.
It’s about spending better.
If something genuinely matters to you and fits comfortably within your financial plan, there may be little reason to eliminate it simply because it isn’t essential.
Perhaps you value travel.
Perhaps you enjoy eating out with friends.
Perhaps fitness is important to you.
Perhaps you enjoy technology, books or a particular hobby.
Give those priorities a place in your budget.
At the same time, reduce spending in areas that provide little value.
This creates a powerful principle:
Spend less on what doesn’t matter so you can spend intentionally on what does.
That approach can make budgeting feel less like deprivation and more like a system for directing your money toward the life you want.
The next step is protecting the progress you are making. A good budget should not only control everyday spending—it should also help you prepare for unexpected expenses, debt and periods when your financial situation changes.
Build Financial Protection
A budget is not only about controlling what you spend today. It should also help protect you from financial problems tomorrow.
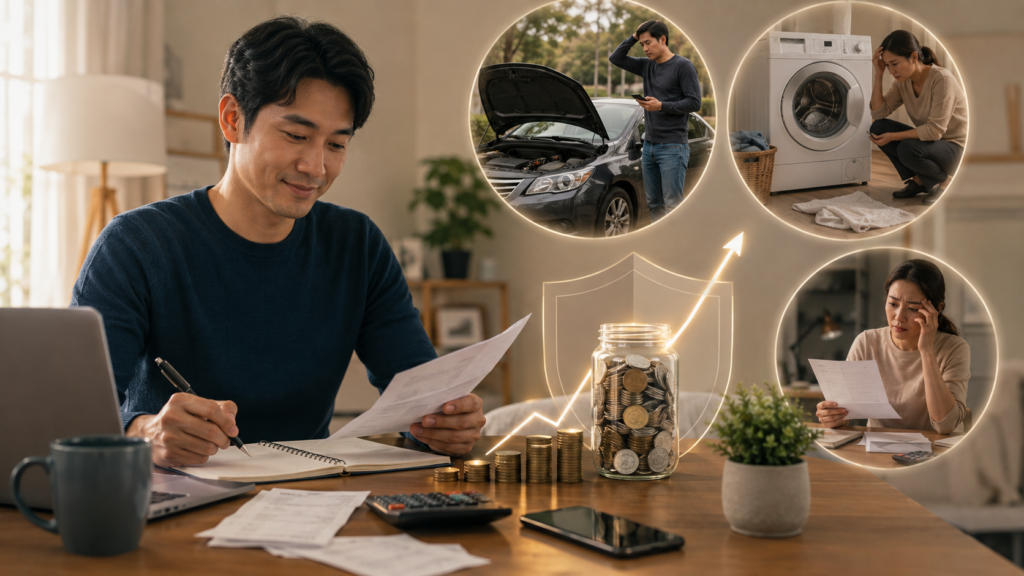
Unexpected expenses are a normal part of life. A car may need repairs. An appliance can break. A bill may be larger than expected. Your income could temporarily decrease. Without a financial buffer, even a relatively manageable problem can turn into expensive debt.
This is why budgeting should include financial protection.
The goal is to gradually create enough flexibility that an unexpected expense does not immediately destroy your monthly plan.
Build an Emergency Fund
An emergency fund is money set aside specifically for unexpected and necessary expenses.
It can help with situations such as:
- Unexpected vehicle repairs
- Essential household repairs
- Sudden travel for an emergency
- Temporary loss of income
- Unexpected essential bills
- Other genuine financial emergencies
The important distinction is that an emergency fund is not the same as ordinary savings.
Money you are saving for a holiday or a new phone is intended to be spent.
Emergency savings are designed to provide a financial safety net when something unexpected happens.
💰 Smart Money Tip: Keep emergency savings separate from your everyday spending money if possible. The harder it is to spend accidentally, the more useful the fund can be when a genuine emergency occurs.
Start Small if Necessary
Many beginners hear advice about building several months of expenses and immediately feel overwhelmed.
You don’t need to create a large emergency fund overnight.
If you currently have nothing saved, your first target could simply be a small financial buffer.
For example:
First goal: $250
Next goal: $500
Next goal: $1,000
After reaching each milestone, you can continue building according to your circumstances.
The exact amount you need depends on factors such as your income stability, household responsibilities, essential expenses and access to other financial resources.
The important thing is to start.
Even a modest emergency fund can be more useful than having no buffer at all.
Think in Terms of Essential Expenses
When considering how much emergency savings you need, your monthly essential expenses can provide a useful starting point.
Suppose your essential monthly costs are:
- Housing: $1,200
- Food: $450
- Utilities: $200
- Transportation: $250
- Insurance: $150
- Minimum debt payments: $250
Your essential monthly expenses would be:
$2,500
You could then use this figure to think about longer-term emergency savings.
For example, three months of essential expenses would be:
$2,500 × 3 = $7,500
This doesn’t mean everyone must have exactly $7,500.
It simply provides a way to think about the size of your financial safety net.
Someone with highly stable employment may approach the calculation differently from someone whose income varies significantly.
📊 Financial Background: Emergency-fund recommendations are often expressed in terms of months of essential expenses because income replacement is one of the major purposes of an emergency reserve. The appropriate amount varies according to individual circumstances.
Keep Emergency Money Accessible
Emergency savings should generally be kept somewhere that allows you to access the money when you genuinely need it.
The purpose of an emergency fund is not necessarily to maximize investment returns.
It is to provide financial availability and stability.
For that reason, consider the difference between:
Money needed soon
and
Money intended for long-term growth
Money required for emergencies has a different purpose from money being invested for long-term goals.
Before choosing a savings product, consider factors such as access, fees, interest, account conditions and the rules applicable in your country.
Prepare for Predictable Emergencies
Some expenses feel like emergencies even though they are actually predictable.
If your car is several years old, maintenance will eventually be required.
If you own a home, repairs will eventually occur.
If insurance is paid annually, that bill will return.
These aren’t necessarily emergencies in the strict sense.
They are irregular expenses.
That’s why it helps to have both:
Emergency savings
and
planned sinking funds
For example:
| Financial reserve | Purpose |
|---|---|
| Emergency fund | Unexpected genuine emergencies |
| Car fund | Maintenance and repairs |
| Annual bills fund | Predictable yearly expenses |
| Holiday fund | Planned travel |
| Home maintenance fund | Expected property costs |
Separating these purposes makes your financial system easier to manage.
Understand Your Debt
Debt isn’t automatically bad.
Borrowing can help people purchase homes, obtain education, manage large necessary expenses or acquire assets that would otherwise be difficult to afford.
The problem arises when debt becomes difficult to control.
Start by making a list of your debts.
Record:
- Balance
- Interest rate
- Minimum payment
- Payment frequency
- Remaining term
- Fees or charges
Seeing the complete picture is important.
A debt that looks manageable on its own may become problematic when combined with several other repayments.
Understand High-Interest Debt
Interest is the price you pay for borrowing money.
If a debt has a high interest rate, a significant portion of your payment may go toward interest rather than reducing the amount you owe.
This is why understanding interest rates matters when creating a budget.
Suppose you owe $5,000 on a debt with a high annual interest rate.
If you make only minimum payments, the debt may take considerably longer to repay and cost substantially more than the original amount borrowed.
The exact cost depends on the interest rate, repayment structure, fees and payment schedule.
📊 Financial Background: Compound interest can work in your favour when you save and against you when high-cost debt remains unpaid. Understanding how interest accumulates is therefore an important part of financial planning.
Choose a Debt-Repayment Strategy
Once you understand your debts, you can consider different repayment approaches.
Two commonly discussed strategies are the debt avalanche and debt snowball methods.
Debt avalanche
Focus additional payments on the debt with the highest interest rate while maintaining required payments on other debts.
This approach can reduce the total interest paid when applied appropriately.
Debt snowball
Focus additional payments on the smallest balance first while maintaining required payments on other debts.
This can provide psychological motivation because smaller balances disappear more quickly.
Neither approach needs to be treated as a universal rule.
The important thing is to maintain required payments and choose a strategy that is realistic for your circumstances.
If you are dealing with significant financial difficulty, professional financial or debt advice may be appropriate.
Don’t Use Credit to Hide Overspending
A credit card can be a useful payment tool when managed responsibly.
But it becomes dangerous when it is used to make a budget appear balanced.
For example:
Income: $3,000
Expenses: $3,300
Credit card: $300
The budget hasn’t actually balanced.
The missing $300 has simply become debt.
If this pattern continues, interest and repayments can make future budgets even harder.
A healthy budget should reflect what you can realistically afford rather than relying on borrowing to cover regular overspending.
⚠️ Budgeting Warning: Using credit to repeatedly cover ordinary living expenses can create a cycle in which today’s spending reduces tomorrow’s available income.
Protect Your Budget From Income Changes
Your financial situation may not remain constant.
You could receive:
- A pay rise
- A bonus
- Fewer working hours
- A period of unemployment
- A change in household income
- A new financial responsibility
Your budget should be able to adapt.
When income increases, avoid automatically increasing every expense.
Consider directing some of the additional money toward:
- Emergency savings
- Debt reduction
- Long-term savings
- Important financial goals
When income decreases, prioritize essential expenses first.
A flexible budget is much more resilient than one that assumes your financial circumstances will never change.
Have a Plan for Unexpected Bills
When an unexpected bill arrives, don’t immediately panic.
Ask:
Is this a genuine emergency?
Can it be postponed?
Do I already have money allocated for this type of expense?
Can I reduce another discretionary expense temporarily?
Would using emergency savings be appropriate?
This prevents every unexpected expense from automatically becoming a new debt.
For example, if your washing machine suddenly breaks and you have an emergency fund, using part of that fund for the replacement may be exactly what the fund was designed for.
You can then rebuild the emergency savings afterward.
Rebuild Your Emergency Fund After Using It
Using emergency savings is not a budgeting failure.
That is what the money is there for.
Suppose you have $3,000 saved and need $800 for an unexpected essential repair.
You now have:
$3,000 − $800 = $2,200
The next step is not to feel guilty.
It is to rebuild the $800 when your budget allows.
This is one reason emergency funds should be viewed as revolving financial protection, rather than a target that you reach once and never touch.
🧠 CurioReader Insight: An emergency fund isn’t successful because you never use it. It is successful when it prevents a genuine emergency from becoming a much larger financial problem.
Protect Yourself From Financial Overconfidence
A healthy bank balance can create a temptation to increase spending.
You might think:
“I have plenty of money, so I can afford this.”
But your current balance doesn’t necessarily represent your available spending money.
Some of it may already be needed for:
- Upcoming bills
- Annual expenses
- Debt payments
- Emergency savings
- Financial goals
Before making a large purchase, consider what obligations are coming next.
A useful question is:
How much of this money is genuinely available after everything I’ve already committed to?
This simple habit can prevent many budgeting mistakes.
Create Financial Breathing Room
Ultimately, financial protection is about creating breathing room.
If every dollar of your income is already committed, even a small problem can cause stress.
If you have some savings, manageable debt and a realistic spending plan, you have more options.
You can respond to unexpected events without immediately relying on expensive borrowing.
That flexibility is one of the most valuable outcomes of budgeting.
Money management isn’t simply about maximizing the amount in your bank account.
It is also about creating financial resilience.
🛡️ CurioReader Insight: Financial security is not the absence of unexpected problems. It is having enough preparation and flexibility to deal with those problems without allowing them to derail your entire financial life.
Once your budget covers everyday spending and provides some protection against financial shocks, the final challenge is making the system sustainable.
A budget that works for one month is useful.
A budgeting habit that continues for years is far more powerful.
Make Your Budget Work Long Term
Creating a budget is relatively easy.
The harder part is continuing to use it when life changes.
Your income may change. Your bills may increase. Your priorities may shift. You may have an unusually expensive month or spend more than you planned.
A successful budgeting system therefore needs to be simple, flexible and sustainable.
The objective isn’t to follow the exact same numbers forever. It is to create a financial habit that helps you make better decisions as your circumstances change.
Review Your Budget Regularly
A budget shouldn’t be something you create once and forget.
A short review can help you identify problems before they become significant.
You might review your finances:
- Once a week for spending awareness
- Once a month for a full budget review
- Every few months for larger financial goals
- Whenever your income or major expenses change
During a monthly review, compare:
What I planned to spend
versus
What I actually spent
The differences are useful information.
If you consistently spend more on groceries than expected, your grocery category may need adjustment.
If you regularly have money left in your entertainment category, you might redirect some of it toward another priority.
The purpose isn’t to punish yourself for differences.
It is to make your budget increasingly accurate.
📊 Financial Background: Budgeting works best as a feedback system. Comparing planned and actual spending gives you information that can be used to improve future decisions.
Don’t Treat Overspending as Failure
Almost everyone will occasionally spend more than planned.
Perhaps you went out with friends.
Perhaps an unexpected purchase was necessary.
Perhaps you simply made a poor spending decision.
One bad week doesn’t mean your entire financial plan has failed.
Instead, ask:
What happened?
Was it a one-time event or a recurring pattern?
Does my budget need to change?
What can I do differently next time?
For example, if you repeatedly spend more on restaurants than planned, you have two choices.
You could create a more realistic restaurant budget.
Or you could identify ways to reduce restaurant spending.
Often, the best answer is a combination of both.
🧠 CurioReader Insight: A budget should create awareness, not guilt. If a budgeting system makes you afraid to look at your bank account after overspending, it isn’t helping you build a healthy long-term financial habit.
Automate What You Can
Automation can reduce the number of financial decisions you need to make manually.
Depending on what your bank and financial providers offer, you may be able to automate:
- Regular savings
- Bill payments
- Debt payments
- Transfers between accounts
- Other recurring financial commitments
For example, you could arrange for a predetermined amount to move into a savings account shortly after receiving your income.
This can make saving more consistent.
However, automation should not mean ignoring your finances.
Check that automated payments are still appropriate and that your account contains enough money to cover them.
Use Separate Accounts or Categories
Some people find budgeting easier when different purposes are separated.
For example, you might have:
Everyday spending
Money for normal purchases.
Bills
Money reserved for regular financial commitments.
Savings
Money being accumulated for financial goals.
Emergency fund
Money reserved for genuine unexpected needs.
The exact structure is up to you.
You don’t necessarily need multiple bank accounts. A budgeting app or spreadsheet can provide the same separation through categories.
The purpose is simply to make it easier to understand what money is available and what money already has a job.
Set Short-, Medium- and Long-Term Goals
A budget becomes more meaningful when it connects everyday decisions to future objectives.
Consider dividing your goals into three time horizons.
Short-term goals
These might include:
- Building a small emergency buffer
- Paying an upcoming annual bill
- Buying necessary equipment
- Saving for a short trip
Medium-term goals
These could include:
- Replacing a vehicle
- Completing further education
- Building a larger emergency reserve
- Saving for a major purchase
Long-term goals
These may include:
- Retirement
- Home ownership
- Long-term investments
- Financial independence
You don’t need to pursue every goal simultaneously.
Choose a small number of priorities and allocate money toward them consistently.
🎯 Smart Money Tip: Give your savings a name. “Emergency fund” or “holiday fund” can be more motivating than simply seeing an unexplained balance increase in a savings account.
Increase Your Savings When Your Income Rises
A pay rise, bonus or additional income can provide an opportunity to improve your financial position.
But it’s easy for additional income to disappear through lifestyle inflation.
Instead of automatically increasing all your expenses, consider dividing additional income between:
- Saving
- Debt reduction
- Long-term goals
- Lifestyle improvements
For example, if your monthly income increases by $300, you don’t necessarily need to spend the entire $300.
You might decide that part goes toward savings while the remainder improves your lifestyle.
There is no universal percentage that you must use.
The important principle is to make the decision before the additional money becomes normal spending.
Revisit Your Budget After Major Life Changes
Your budget should change when your circumstances change.
Review it when you:
- Change jobs
- Receive a significant pay rise or pay cut
- Move home
- Take on new debt
- Pay off a loan
- Start or end a relationship
- Have children
- Retire
- Start a business
- Experience a major change in living costs
A budget created for one stage of life may not work for another.
For example, someone renting a small apartment and living alone will have very different expenses from a household with children and a mortgage.
Flexibility is therefore essential.
Don’t Forget to Budget for Enjoyment
Financial discipline doesn’t mean eliminating everything enjoyable.
In fact, deliberately budgeting for enjoyment can make your overall financial system easier to maintain.
You might allocate money for:
- Eating out
- Entertainment
- Hobbies
- Travel
- Personal purchases
- Social activities
The amount depends on your circumstances.
The key is that the spending is planned and affordable.
If you have already allocated $150 for entertainment and spend it on activities you genuinely enjoy, that is not necessarily a budgeting failure.
You followed your plan.
💡 CurioReader Insight: A sustainable budget should leave room for living your life today while protecting your ability to live well in the future.
Use Technology Without Becoming Dependent on It
There are many tools available for managing money.
You can use:
- Banking apps
- Budgeting applications
- Spreadsheets
- Calendar reminders
- Automatic transfers
- Financial dashboards
Technology can make tracking easier.
But the tool itself doesn’t create financial discipline.
You can have the most sophisticated budgeting application available and still overspend.
Conversely, a simple spreadsheet can work extremely well if you actually use it.
Choose the simplest system that gives you enough information to make good decisions.
Create a Monthly Money Routine
One of the easiest ways to make budgeting a long-term habit is to create a regular routine.
For example, at the beginning of each month:
1. Check income
Confirm expected income for the month.
2. Review upcoming bills
Identify major expenses and irregular payments.
3. Allocate savings
Move planned savings into the appropriate accounts or categories.
4. Set spending limits
Decide how much is available for variable and discretionary expenses.
5. Check financial goals
Review progress toward savings and debt objectives.
At the end of the month:
6. Compare planned versus actual spending
7. Identify problems
8. Adjust next month’s budget
This process doesn’t have to take hours.
A short, consistent review can be enough.
What to Do When Your Budget Is Too Tight
Sometimes the problem isn’t poor spending discipline.
Your essential expenses may simply be too high compared with your income.
If that happens, repeatedly cutting small discretionary purchases may not solve the underlying problem.
Look at the bigger picture.
Could you:
- Reduce a major recurring expense?
- Change an expensive service?
- Increase working hours?
- Develop an additional income stream?
- Improve your qualifications?
- Renegotiate certain costs?
- Seek appropriate financial advice?
Budgeting can reveal when the issue is not simply spending too much, but rather having too little income relative to essential costs.
This distinction is important.
A person shouldn’t be made to feel that every financial difficulty is caused by buying coffee or occasional entertainment.
Sometimes the mathematics simply doesn’t work.
Give Every Extra Dollar a Purpose
When you have money left over after your planned expenses, don’t automatically assume it should be spent.
Consider giving it a purpose.
It could go toward:
- Emergency savings
- High-interest debt
- A future purchase
- A long-term financial goal
- Investment, where appropriate
- Something you genuinely value
The right choice depends on your financial circumstances.
The important thing is to make the decision deliberately.
This is the fundamental principle behind good budgeting:
Money should have a purpose before it disappears.
Focus on Progress, Not Perfection
Perhaps the most important long-term budgeting principle is to avoid expecting perfection.
You may overspend occasionally.
You may forget to track something.
You may have an expensive month.
You may change your priorities.
None of these automatically means budgeting has failed.
What matters is whether you return to the system.
Think of budgeting as a financial navigation tool.
If you make a wrong turn while driving, you don’t normally abandon the entire journey.
You adjust your route.
Your budget works in much the same way.
🧠 CurioReader Insight: Financial progress is measured over months and years, not by whether every single day was perfect. Consistent improvement is more valuable than temporary financial perfection.
The Goal Is Financial Freedom of Choice
Ultimately, budgeting isn’t really about spreadsheets, restrictions or saying “no” to every purchase.
It is about creating choices.
When you understand your finances, you can make decisions with greater confidence.
You can decide whether you can afford a holiday.
You can prepare for an unexpected repair.
You can work toward paying off debt.
You can save for something important.
You can enjoy a purchase without wondering whether it will cause problems later.
You can make career or lifestyle decisions with a clearer understanding of your financial position.
That is the real value of budgeting.
It gives your money direction.
And when your money has direction, your financial decisions become less reactive and more intentional.
A good budget doesn’t tell you how to live.
It helps you make sure your money supports how you choose to live.
With that foundation in place, the final step is to bring everything together into a simple set of principles you can use to manage your money with greater confidence.
Key Takeaways
Smart budgeting isn’t about restricting every purchase or following a perfect financial formula. It is about understanding your money and making deliberate decisions about where it goes.
The most important principles are:
- Know your income: Understand how much money you actually have available after deductions.
- Track your spending: You can’t manage spending effectively if you don’t know where your money is going.
- Separate needs from wants: This helps identify where you have flexibility when money is tight.
- Create a realistic budget: Use your actual expenses rather than unrealistic spending targets.
- Choose a method that suits you: The 50/30/20 rule, zero-based budgeting and pay-yourself-first approaches are useful options, but none is mandatory.
- Plan for irregular expenses: Annual bills and predictable repairs should not always be treated as emergencies.
- Reduce spending strategically: Focus on expenses that provide little value rather than eliminating everything enjoyable.
- Build an emergency fund: Even a small financial buffer can provide valuable protection.
- Understand your debt: Know your balances, interest rates and repayment obligations.
- Automate where appropriate: Automatic savings and bill payments can make good financial habits easier to maintain.
- Review your budget regularly: Your budget should change when your income, expenses or priorities change.
- Allow room for enjoyment: A sustainable budget should support your quality of life as well as your financial goals.
- Focus on consistency: A budget you can follow for years is more valuable than an extreme plan you abandon after a few weeks.
🧠 CurioReader Insight: The strongest budgeting habit is not finding a perfect system. It is regularly knowing where your money is going and making conscious decisions about what happens next.
Frequently Asked Questions
What is the easiest budgeting method for beginners?
There is no single best method for everyone. A simple approach is to list your income, essential expenses, savings goals and discretionary spending. Beginners can also experiment with frameworks such as the 50/30/20 rule and then adjust the categories to fit their circumstances.
How much money should I save each month?
There is no universal amount that applies to everyone. Your savings capacity depends on your income, essential expenses, debt, financial responsibilities and goals.
The important thing is to establish a sustainable amount and increase it when your financial situation allows.
Even starting with a small amount can help establish the habit of saving.
Is the 50/30/20 budgeting rule suitable for everyone?
No. The 50/30/20 rule is a useful framework, but it isn’t a requirement.
Someone with high housing costs may spend considerably more than 50% on needs. Someone aggressively paying down debt may allocate much more than 20% toward debt and savings.
Use the rule as a starting point rather than a rigid target.
Should I save money or pay off debt first?
The answer depends on the type and cost of your debt, your existing savings and your overall financial circumstances.
Maintaining required debt payments is important. Building at least some emergency savings can also help prevent unexpected expenses from creating additional debt.
High-interest debt may deserve particular attention because interest can significantly increase the cost of borrowing.
How much should an emergency fund contain?
The appropriate amount depends on your circumstances, including income stability, essential expenses and financial responsibilities.
A useful way to begin is to calculate your essential monthly expenses and then work toward building a reserve that could cover a period of necessary costs.
If you currently have no emergency savings, starting with a smaller initial target can make the goal more manageable.
How can I budget if my income changes every month?
If your income is irregular, consider creating your essential budget around a conservative estimate rather than your highest-income month.
During stronger months, you may be able to build savings, prepare for future expenses or reduce debt.
The key is to avoid committing to fixed expenses that depend on receiving unusually high income every month.
What should I do if I go over my budget?
Don’t abandon your budget.
First determine why you overspent.
Was the expense unexpected? Was your original budget unrealistic? Was the spending discretionary?
Then adjust accordingly.
One difficult month doesn’t erase months of progress.
Should I use a budgeting app?
A budgeting app can be helpful, but it isn’t essential.
You can manage your finances using a spreadsheet, banking tools, a notebook or another method that you find easy to maintain.
The best system is the one that gives you enough information to make informed decisions and that you will actually continue using.
How can I stop impulse spending?
Try introducing a waiting period for non-essential purchases.
A 24-hour pause can be enough for smaller purchases, while larger purchases may benefit from a longer waiting period.
You can also remove saved payment details, unsubscribe from promotional emails and create a specific discretionary spending limit.
Is budgeting only for people who have financial problems?
No.
Budgeting can benefit people across a wide range of financial circumstances.
Someone struggling financially may use a budget to identify unnecessary expenses and prioritize essential bills.
Someone with a comfortable income may use one to improve saving, manage lifestyle inflation and work toward long-term goals.
The purpose is not simply to spend less.
It is to make better use of the money available.
Conclusion
Managing money well doesn’t require complicated financial knowledge.
It begins with a few straightforward habits:
Know what you earn.
Know what you spend.
Plan where your money should go.
Prepare for unexpected expenses.
Review your decisions regularly.
A good budget gives you visibility over your financial life. It helps you see whether your everyday spending is supporting your priorities or quietly working against them.
It can also change the way you think about money.
Instead of asking only:
“Can I afford this?”
you can start asking:
“Does this fit into the financial plan I want for myself?”
That is a much more useful question.
Budgeting also shouldn’t be viewed as a punishment. You don’t need to eliminate every coffee, restaurant meal, hobby or holiday to manage money responsibly.
The objective is to understand the difference between spending intentionally and spending automatically.
If something genuinely matters to you and you can afford it, make room for it.
If something provides little value, consider reducing it.
If a financial goal is important, give it a place in your budget.
💰 Smart Money Tip: Before making a purchase, think beyond the price tag. Consider what else that money could accomplish if you saved it, used it to reduce debt or directed it toward an important financial goal.
Over time, small decisions can become meaningful financial habits.
Saving a modest amount every month can become a substantial reserve.
Reducing unnecessary recurring expenses can free money for important goals.
Making additional debt payments, when appropriate, can reduce future interest costs.
Planning for irregular expenses can make unexpected bills less disruptive.
None of these actions requires perfection.
They require consistency.
🧠 CurioReader Insight: Financial progress is usually built through repeated decisions rather than one dramatic change. A simple system that you follow consistently can be more powerful than an elaborate strategy that you rarely use.
There will be months when your budget doesn’t work perfectly.
You may spend more than planned.
An unexpected expense may appear.
Your income may change.
Your priorities may be different from what they were six months ago.
That’s normal.
The solution isn’t to abandon budgeting.
It is to review, adjust and continue.
Think of your budget as a financial navigation system.
It helps you understand where you are, where you want to go and whether your current direction is taking you there.
You can change the route when circumstances change.
What matters is that you remain aware of the destination.
Ultimately, smart budgeting is about more than numbers.
It is about creating financial breathing room, reducing unnecessary stress and giving yourself more choices.
When you know where your money is going, you can make decisions with greater confidence.
You can prepare for emergencies.
You can work toward meaningful goals.
You can enjoy the money you spend without constantly wondering whether you’ve made a mistake.
And perhaps most importantly, you can make your money serve your priorities rather than allowing your spending habits to decide your priorities for you.
You don’t need to control every cent to manage money well. You simply need to understand your money, give it a purpose and review your plan regularly.
That is the foundation of smart budgeting—and a practical first step toward greater financial confidence and long-term financial stability.
Further Reading & Resources
Continue your learning journey with more expert guides and insightful articles from CurioReader. Explore related topics below to deepen your understanding and discover new perspectives.
Related CurioReader Articles
- The Complete Beginner’s Guide to Personal Finance: 10 Essential Money Skills Everyone Should Learn.
- What Is Cryptocurrency? A Beginner’s Guide to the Exciting World of Digital Money.
Recommended External Resources